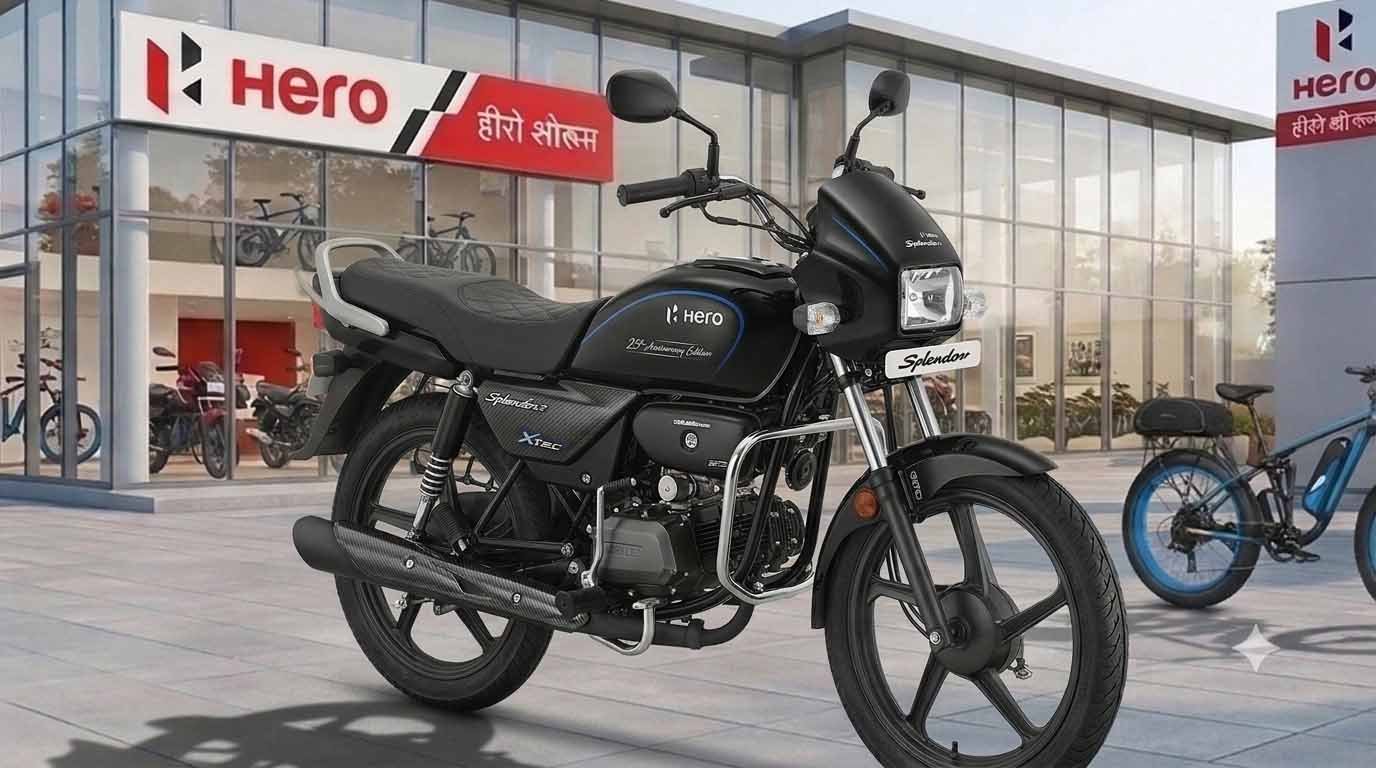
The Hero Splendor Plus is a commuter motorcycle designed for everyday travel. Buyers who prefer to spread its purchase cost over time may consider a two-wheeler loan. Under this arrangement, a bank or finance company may pay the approved amount towards the purchase, while the borrower repays the lender through monthly instalments.
However, loan approval and affordability depend on several factors, including the applicant’s income, repayment capacity, credit history, required down payment and the lender’s current policies. Interest rates and charges can also differ between finance providers.
This article explains Hero Splendor Plus loan eligibility, interest rates, documents, monthly instalments and the steps buyers can take to compare finance options responsibly.
Understanding Hero Splendor Plus Loans
A two-wheeler loan is a financing arrangement intended to help an eligible customer purchase a motorcycle. The lender assesses the application and decides the amount it is willing to finance, the interest rate, repayment tenure and other conditions.
The buyer generally contributes a down payment and repays the approved loan through EMIs. The loan agreement explains the repayment schedule and any applicable charges.
Hero MotoCorp’s official website provides information about the Splendor Plus and an online EMI calculator. Hero FinCorp also publishes information about two-wheeler loans for the Hero Splendor Plus. These are useful starting points for checking available options, but the final terms depend on the lender’s assessment and current offer.
Hero Splendor Plus Loan Eligibility Criteria
There is no single eligibility rule that applies to every finance provider. Lenders may consider the following factors when reviewing an application.
1. Minimum Age
The applicant must meet the lender’s minimum-age requirements and be legally eligible to enter the loan agreement. The required age can vary by lender and product.
2. Income and Repayment Capacity
Lenders may assess whether the applicant has sufficient and reasonably stable income to repay the proposed EMI. Salary, business income or other acceptable income sources may be considered under the lender’s rules.
3. Employment or Business Details
A lender may ask for employment information, salary records or business documents. Self-employed applicants may be asked to provide different evidence from salaried applicants.
4. Credit History
Credit history can help lenders understand how an applicant has handled previous borrowing. A strong record may improve the chances of receiving favourable terms, but approval is never guaranteed.
Applicants with limited credit history should ask the lender which documents and alternative assessments it accepts.
5. Existing Financial Commitments
Existing loans, credit-card payments and other financial commitments may affect how much a lender is willing to approve. The lender may assess the proposed EMI alongside the applicant’s existing obligations.
6. Identity and Address Verification
Applicants must provide the information and documents required for identity verification, address confirmation and other applicable checks.
Meeting these conditions does not automatically mean a loan will be approved. The final decision rests with the finance provider.
Hero Splendor Plus Loan Interest Rates
The interest rate determines how much the lender charges for providing the loan. Rates may vary according to the lender, loan amount, repayment tenure, applicant profile and current lending policies.
Hero FinCorp’s published Hero Splendor Plus loan page advertises rates starting at 14% per year, while also describing eligibility and tenure conditions. This is a lender-specific advertised starting rate, not a guaranteed offer for every customer. The rate available to an individual applicant may be different.
When comparing lenders, check whether the advertised rate applies to your circumstances. Ask for the annual rate, method of interest calculation, processing fee, late-payment charges and other applicable costs in writing.
A lower advertised rate is not always the cheapest overall option if the loan has higher fees or less favourable conditions.
Factors That Affect the Interest Rate
Several factors may influence the rate a lender offers.
Credit record: Previous repayment behaviour and the available credit history may affect the lender’s assessment.
Loan amount: The amount requested may affect which products or terms are available.
Repayment tenure: The selected tenure can affect the instalment and total interest paid.
Applicant profile: Income stability, existing financial obligations and other eligibility factors may be considered.
Lender policies: Different banks and finance companies use their own underwriting rules and pricing structures.
Applicants should compare actual written offers rather than relying on general online estimates.
Down Payment and Loan Amount
The down payment is the portion of the motorcycle’s purchase cost paid by the buyer instead of being financed. The amount required depends on the on-road price and the lender’s financing rules.
For example, if a motorcycle’s total on-road cost is ₹90,000 and a lender approves a loan of ₹72,000, the buyer would need to contribute ₹18,000 towards that cost. Any additional charges excluded from the quotation or loan would need to be considered separately.
This is an illustrative example, not a current price quotation or guaranteed loan offer.
A larger down payment reduces the amount borrowed and can reduce the EMI and total interest. However, buyers should retain enough money for essential expenses and future motorcycle maintenance.
Affordable Monthly Installments for Hero Splendor Plus
An EMI is the scheduled monthly payment made towards a loan. It generally includes principal repayment and interest.
The monthly amount depends on the principal, interest rate and tenure. A longer repayment period usually lowers the EMI but may increase total interest. A shorter tenure generally raises the EMI while potentially reducing the overall interest cost.
The most affordable plan is not necessarily the one with the lowest displayed instalment. It is the plan whose payments fit the buyer’s budget while keeping total borrowing costs reasonable.
Illustrative EMI Example
Suppose an applicant borrows ₹70,000 at an illustrative annual interest rate of 15% for 24 months. Using a standard reducing-balance EMI calculation, the monthly instalment would be approximately ₹3,394.
Across 24 months, the total of the instalments would be approximately ₹81,456, including around ₹11,456 in interest. These figures exclude separate fees or other costs.
This example is for explanation only. The actual EMI will depend on the lender’s approved loan amount, rate, tenure and charges.
How to Calculate Your EMI Online
An online EMI calculator can help estimate the monthly repayment before applying.
- Visit the official Hero MotoCorp website or the chosen lender’s website.
- Open the Splendor Plus product or loan page.
- Enter the amount you expect to borrow.
- Select the interest rate quoted by the lender.
- Choose an available repayment tenure.
- Review the estimated EMI and total repayment.
- Compare the estimate with your budget and the lender’s written offer.
Hero MotoCorp’s Splendor Plus page includes an EMI calculator that lets users adjust the loan amount, interest rate and tenure. Treat the displayed result as an estimate until the lender confirms the final terms.
Documents Required for a Hero Splendor Plus Loan
The required documents vary between lenders. An application may request:
- Accepted identity proof.
- Address proof.
- PAN or other required tax-related information.
- Salary slips, bank statements or other income evidence, if applicable.
- Employment or business details.
- A completed loan application.
- The motorcycle quotation or dealership information.
- Any additional documents requested during verification.
Applicants should confirm the current document checklist with the finance provider. Submit documents only through authorised channels and do not share OTPs or account passwords with anyone claiming to guarantee loan approval.
Steps to Apply for a Hero Splendor Plus Loan
Step 1: Choose the Motorcycle Variant
Compare the available Splendor Plus variants and select one that suits your needs and budget. Check the price for your city and the exact variant.
Step 2: Obtain an On-Road Quotation
Ask an authorised dealership for a written quotation showing the motorcycle price, registration, insurance and other applicable charges.
Step 3: Compare Finance Providers
Review available bank, NBFC and dealership-assisted finance options. Compare the interest rate, processing fee, down payment, tenure and total repayment amount.
Step 4: Submit an Application
Use the lender’s authorised website or follow the dealership’s verified application process. Enter accurate information and provide the required documents.
Step 5: Complete Verification
The lender may verify identity, income, address and credit information. It may request additional documents before reaching a decision.
Step 6: Review the Loan Agreement
Before accepting the loan, check the EMI, payment dates, applicable fees, late-payment conditions and prepayment rules. Keep a copy of the agreement.
Step 7: Complete the Purchase
Once the lender has approved the application and the required formalities are completed, follow the dealership’s instructions for payment and delivery.
How to Improve Your Loan Application
Applicants can prepare by organising their documents, checking the accuracy of their personal information and calculating a realistic monthly budget.
Avoid taking on an instalment that leaves insufficient money for essential expenses. If possible, compare more than one genuine offer and ask for a clear explanation of the total borrowing cost.
Do not submit false information, pay unofficial agents for guaranteed approval or sign blank forms. Approval depends on the lender’s assessment, and no outside person can legitimately promise a particular decision.
Common Questions About Hero Splendor Plus Finance
Can I purchase a Hero Splendor Plus through EMI?
Eligible applicants may be able to use a two-wheeler loan, subject to the finance provider’s current terms and approval.
Is a zero-down-payment loan guaranteed?
No. Financing limits and down-payment requirements vary. Confirm the terms with the lender before assuming that the full purchase cost can be financed.
Does a higher credit score guarantee a lower interest rate?
No. Credit history is only one factor. The lender also considers other eligibility requirements and its own lending policies.
Can I repay the loan early?
Early repayment may be possible, but conditions and charges vary by agreement. Check the lender’s prepayment or foreclosure policy before signing.
Where can I check official finance options?
Start with the official Hero MotoCorp Splendor Plus page and the relevant lender’s website. Verify all current terms directly before applying.
Conclusion
A Hero Splendor Plus loan may help eligible buyers spread the motorcycle’s purchase cost across monthly instalments. To select a suitable plan, understand the eligibility requirements, compare the actual interest rates and fees, and calculate the total repayment rather than focusing only on the EMI.
Obtain a written on-road quotation, check the lender’s documentation requirements and choose a tenure that fits your budget. Reviewing the agreement carefully before accepting the loan can help you avoid unexpected costs and make a better-informed purchase decision.
Disclaimer: This article provides general information and is not a loan approval or financial offer. Interest rates, eligibility rules, prices and fees may change. Confirm the latest details with Hero MotoCorp, an authorised dealership or the finance provider before making a decision.